

💡 MaxDividends Mission: Helping people build growing passive income, retire early, and live off dividends.
For dividend investors seeking opportunities with strong growth potential, MaxDividends Stock Ideas offers a daily, in-depth look at companies worth considering for a dividend portfolio.
Premium partners — this breakdown is just for you.
You’re not here for hype. You’re here for edge. And today’s company is exactly the kind of quiet powerhouse that separates seasoned dividend investors from the crowd.
Here’s the truth nobody debates: people will delay vacations, skip upgrades, tighten grocery budgets… but they will not cut vet bills.
Pets moved from “nice to have” to “family,” and Zoetis built an entire global empire on that unstoppable shift.
They’re not chasing AI headlines or rolling out shiny gadgets. They focus on something far stronger: vaccines, treatments, and diagnostics for dogs, cats, cattle — the essential infrastructure of animal health. The world quietly depends on them, every single day.
And quiet businesses? Those are often the most powerful.
Zoetis converts steady, non-cyclical demand into margins most pharma players would kill for — and a dividend that grows with the precision of a metronome.
For Premium partners who appreciate “essential but overlooked” compounders
Zoetis is your kind of company.
Let’s dive in.
History of the Company
Zoetis traces its roots to the mid‑20th century. In the 1950s, researchers at Pfizer discovered an antibiotic (Terramycin) effective for livestock — marking the beginning of Pfizer’s work in animal health. In 1952 Pfizer formalized this focus by establishing its “Animal Agriculture” division (later renamed Pfizer Animal Health). Over subsequent decades the division expanded its scope — developing and launching medicines and treatments for both livestock and companion animals, and acquiring other animal‑health entities.
In 2012–2013 Pfizer spun off this business. In February 2013 Zoetis completed its initial public offering, and on June 24, 2013, after an exchange offer, Zoetis became fully independent from Pfizer. Since then Zoetis has operated as a standalone global company, focusing exclusively on animal health — developing and marketing vaccines, medicines, diagnostics and other veterinary products for both farm and companion animals.
A Proven Dividend Champion🏆
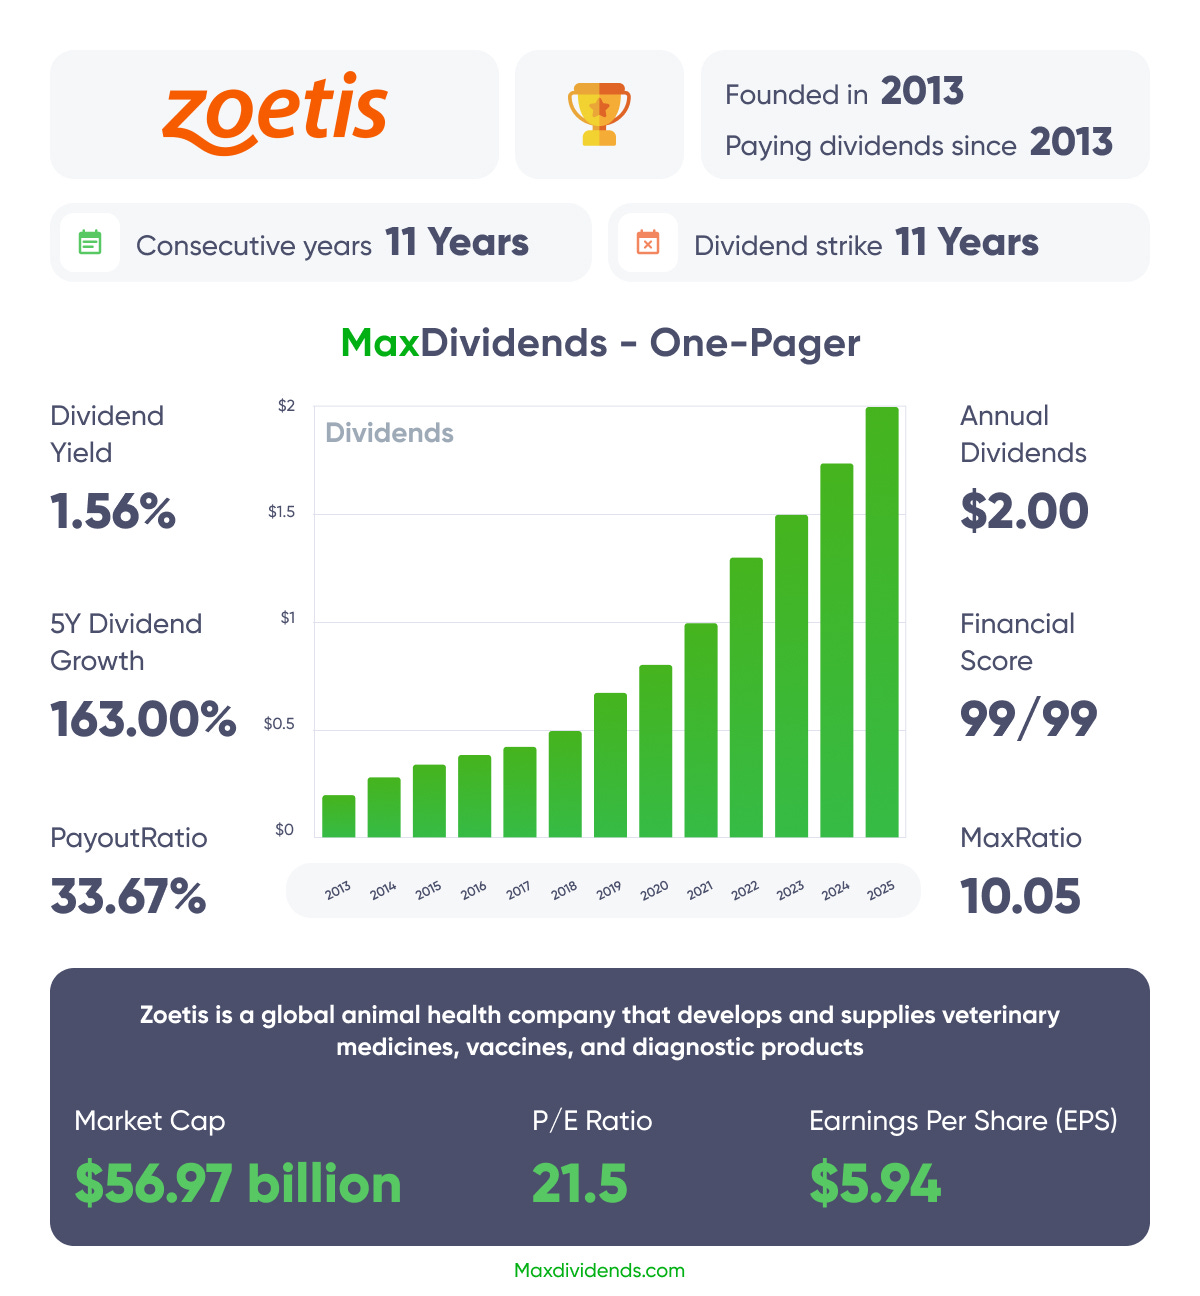
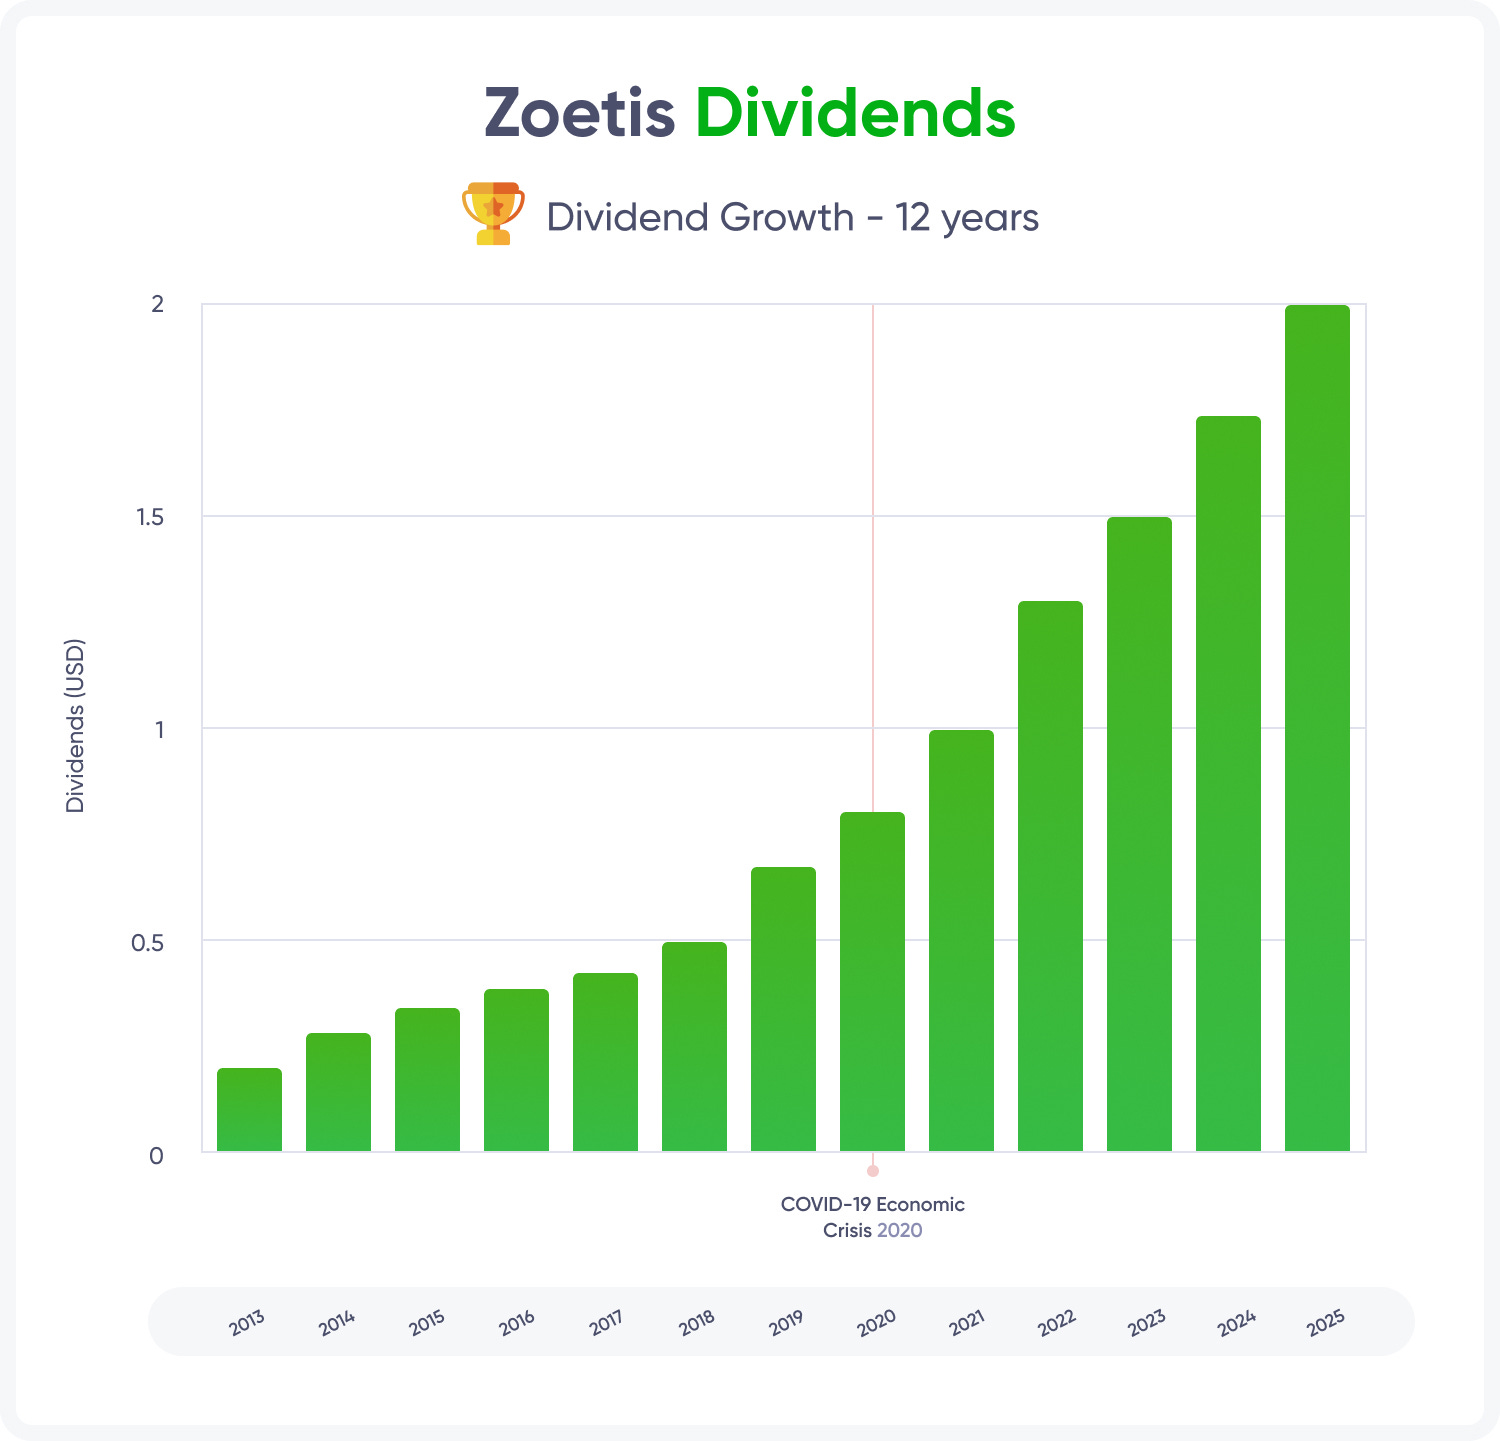
Since 2013 Zoetis has begun regular dividend payments and over the past ~12 years has steadily increased its quarterly payout without interruption. Initially the dividend per share was modest, but every year the company raised it — by 2025 the annual dividend amounts to about $2.00 per share.
That makes dividend growth rather aggressive: growth rates often exceeded 15–30 % per annum. Despite the relatively short track record (just over a decade), the trend of uninterrupted dividend increase shows that Zoetis treats payouts as a growing, strategic commitment rather than a legacy habit.
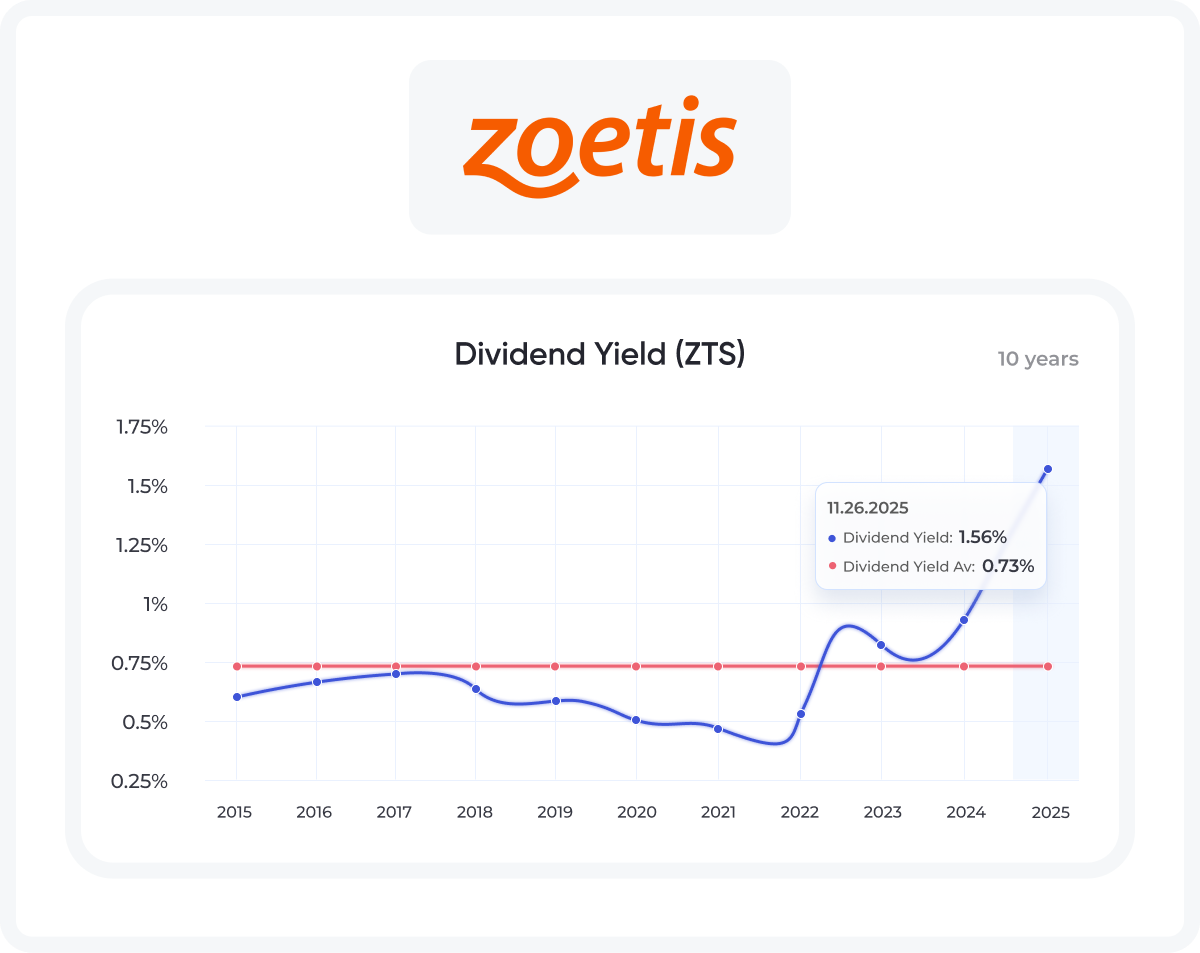
🟢 Current Dividend Yield 1.56% higher than 10 Years Average 0.73% Dividend Yield.
In the MaxDividends app, open the 10-year yield band and set a price/yield alert to ping you when it drifts back into your buy zone.
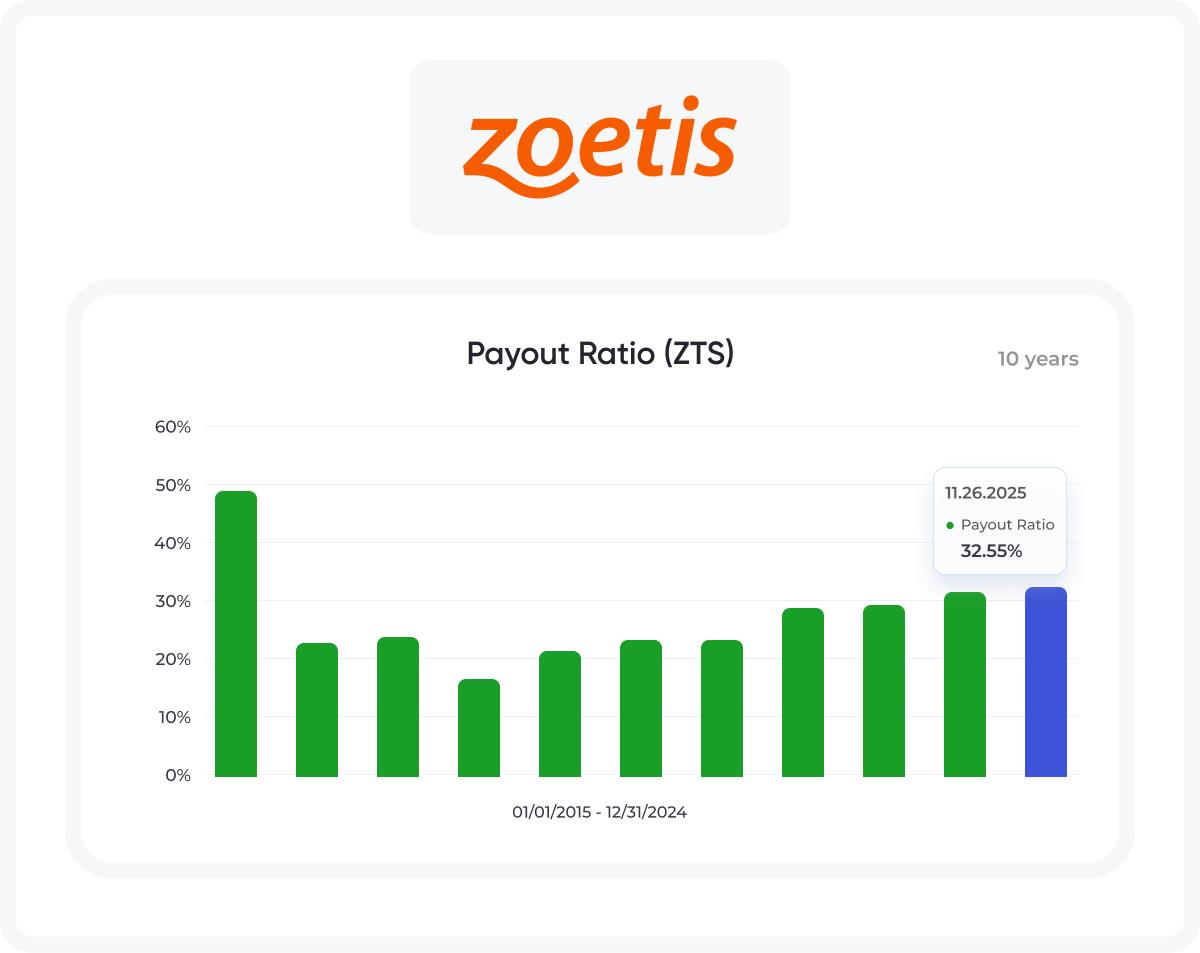
🟢 Current Payout Ratio 32%
That’s a very conservative level — Zoetis covers its dividends comfortably, with plenty of room to grow. A payout ratio around 32% signals strong dividend safety and leaves ample space for reinvestment and expansion. In the MaxDividends app, check the Payout Safety gauge and the forward payout view to confirm stability before adding or reinvesting.
Key Institutional Investors in Zoetis Inc
Zoetis enjoys substantial backing from heavyweight institutional investors — a fact that underscores market confidence in its stable business model and long-term prospects. As of mid‑2025, about 92–94% of Zoetis shares are held by institutional investors.
Among the largest holders:
Vanguard Group, Inc. — ~ 41.9 million shares (≈ 9.4 % of total)
BlackRock, Inc. — ~ 37.2 million shares (≈ 8.4 %)
State Street Corp. — ~ 19.7 million shares (≈ 4.4 %)
State Farm Mutual Automobile Insurance Company — ~ 15.9 million shares (≈ 3.6 %)
Geode Capital Management, LLC — ~ 11.1 million shares (≈ 2.5 %)
Together, these and other institutional holders command the bulk of Zoetis’s free‑float — offering the stock a stable, long‑term oriented investor base.
What Makes Zoetis Stand Out?
Zoetis Inc (NYSE: ZTS)
Business Quality Score: 99 / 99 ⭐️⭐️⭐️⭐️⭐️+
Industry: Drug Manufacturers - Specialty & Generic
Dividend Increase - 12 Years
Zoetis isn’t just another pharmaceutical company — it’s the world’s largest and most diversified animal‑health enterprise, serving pets and livestock alike. Founded on decades of veterinary research and spun out from Pfizer, Zoetis has evolved into a global leader with over 300 product lines and operations in more than 100 countries.
What makes Zoetis stand out is its “animal‑health full‑stack” model: it discovers, develops, manufactures and markets vaccines, medicines, diagnostics and pet/livestock‑specific technologies — covering everything from anti‑parasite treatments and dermatology products to diagnostics, genetic tests and disease‑prevention tools.
But here’s the twist: Zoetis isn’t just “selling pet meds” — it’s a science‑driven global infrastructure business underpinning veterinary care worldwide. Roughly 68% of its revenue today comes from companion animal products (pets), and 31% from livestock, showing strength across very different markets.
Zoetis Inc - Quick MaxDividends Team Overview
🟢 Current reporting data indicates that the company is profitable.

🟢 The company’s sales have shown steady growth over the years, signaling strong business momentum.

🟢 Profitability has improved year after year — a clear sign of smart strategy and execution.

🟢 Earnings are increasing on a per-share basis. That’s good news for both reinvestment and potential dividends.

🟢 The company continues to perform even in difficult years — a sign of resilience.
Historical Context
Zoetis began its regular quarterly dividend payouts soon after its spin‑off and quickly established a pattern of consistent increases. As of the first quarter of 2015, the quarterly dividend was declared at $0.083 per share.
By the first quarter of 2016, the dividend had grown to $0.095 per share (a +14.5% increase).
In 2025, Zoetis declared a quarterly dividend of $0.50 per share for Q1 — a substantial increase, reflecting long‑term growth in shareholder returns.
With MaxDividends App, it’s easier than ever to access top dividend companies, track your results, and explore new dividend ideas.
Financial Statement
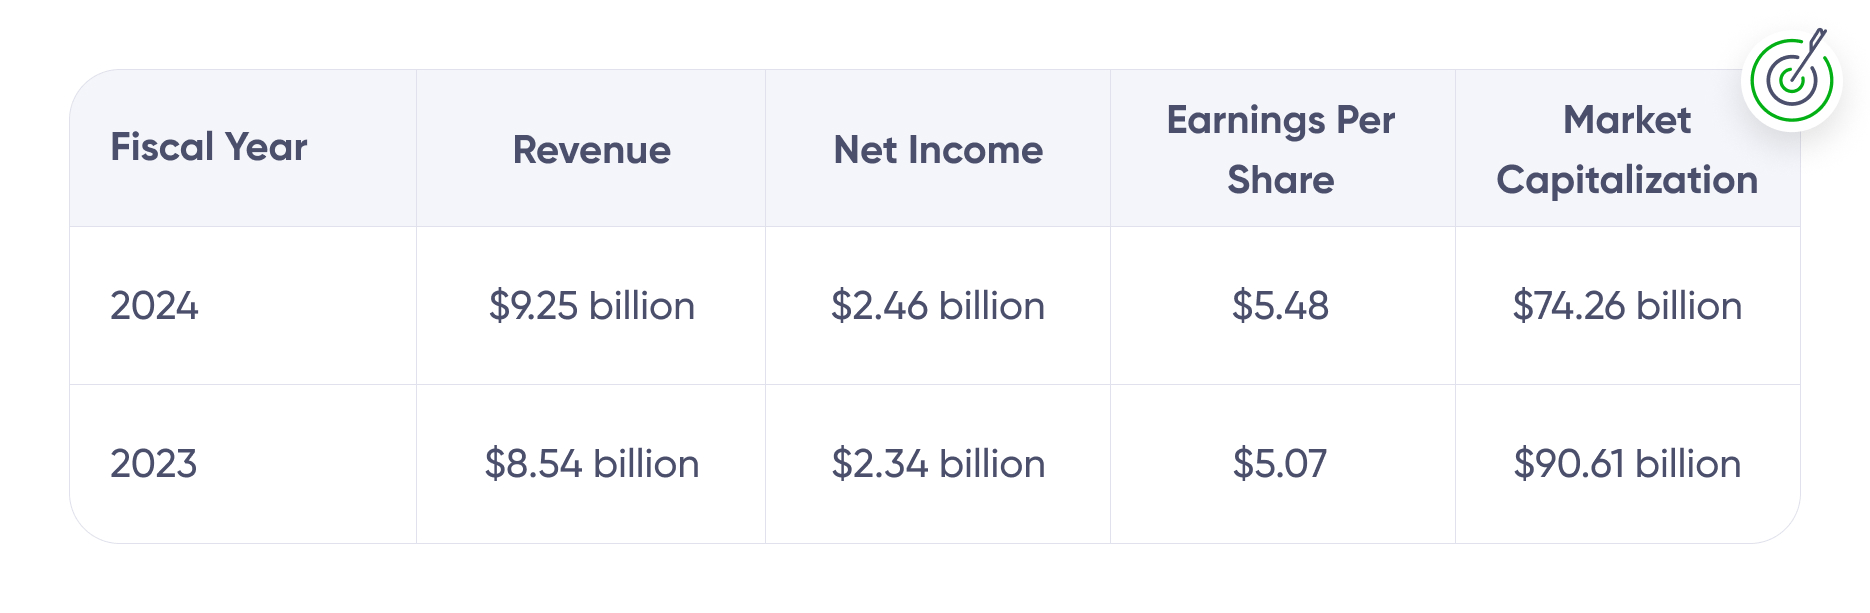
👉 Looking at Zoetis’s numbers, its revenue and net income have shown steady growth in recent years — driven by demand for veterinary drugs, vaccines and diagnostics across both companion animals and livestock. In full‑year 2024 Zoetis generated $9.3 billion in revenue, up ~8 % vs 2023.
Operating performance remained robust: adjusted net income for 2024 reached ≈ $2.7 billion, with adjusted diluted EPS of $5.92. Just in the third quarter of 2025 the company reported $2.4 billion in revenue and $721 million net income (≈ $1.63 per diluted share), with adjusted net income of ~$754 million.
📱 In the MaxDividends snapshot, these numbers show how Zoetis converts its business scale and product‑diversity into stable earnings — exactly the kind of financial strength that underpins a solid dividend track record and long‑term shareholder value.
If you want to stay on top of your portfolio’s health, don’t forget to check in on the financials of the companies you’ve invested in. The better shape they’re in, the better your results will be. Keep an eye on their quarterly and annual reports to see how they’re performing.
The strongest and most stable companies tend to have a Financial Score of 80+, with the very best ones hitting 90+. If you see that score start to dip below 80, that’s your cue to consider jumping ship before things get worse.
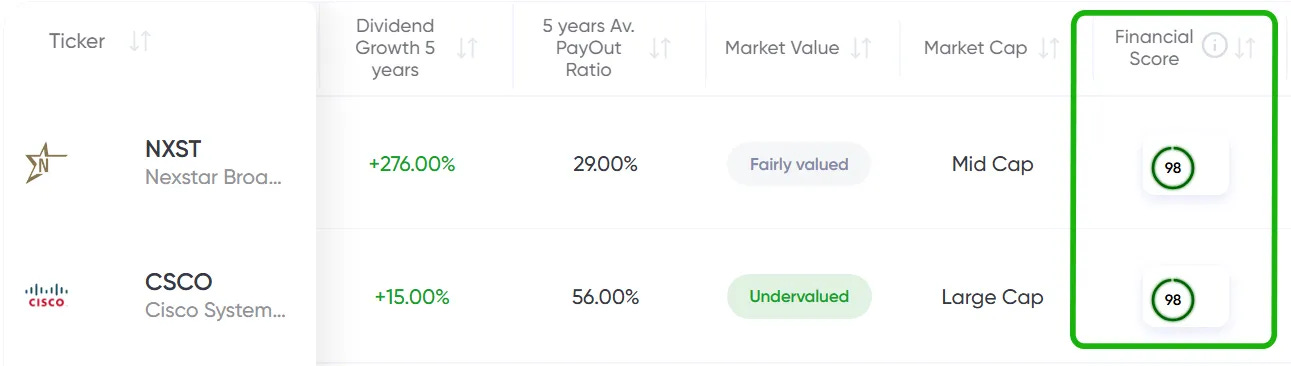

Our Premium Members get access to a curated watchlist of 19,000 companies worldwide, all scored by our team on a regular basis. Companies like Zoetis are on that list, too.
Future Growth Prospects for Zoetis
Zoetis is well-positioned to grow in coming years thanks to its deep pipeline, global footprint and diversified product mix. The company recently forecast organic operational revenue growth of 6–8% in 2025, backed by strong demand for companion-animal products (dermatology, parasite control, OA-pain therapies) and expanding international sales.
A key driver is innovation: Zoetis plans to bring to market new therapies such as long-acting monoclonal-antibody treatments for osteoarthritis pain in dogs and cats (products like Lenivia and Portela), addressing unmet needs and opening growth in chronic-care for pets.
At the same time, Zoetis leverages its global scale and balanced livestock + companion-animal segments to smooth volatility: livestock-focused product approvals and market expansions help diversify revenues, while companion-animal medicines and diagnostics benefit from rising pet ownership and demand for advanced pet-care.
In sum — Zoetis looks more like a long-term “animal-health infrastructure” business than a conventional drugmaker: a mix of recurring demand, innovation-driven growth, and global diversification, which together support a credible path toward sustained revenue and earnings growth.
Why Invest in Zoetis?
Global leader in animal health: Zoetis sells medicines, vaccines, diagnostics and other products for both pets and livestock — covering 8 core species and distributing across 100+ countries.
Balanced business mix: In 2024 roughly 68 % of revenue came from companion-animal products and 31 % from livestock — giving diversification across pet care and food-animal markets.
Innovation-driven growth: Zoetis supports a broad portfolio of ~300 product lines and invests heavily in R&D and lifecycle innovations, enabling consistently strong launches.
Strong financial performance and resilient demand: In 2024 the company earned $9.3 billion in revenue, with growth across major franchises, even as market conditions fluctuated.
Clear growth trajectory & guidance: For 2025 Zoetis expects organic operational revenue growth of 6-8 %, backed by strong demand in its core companion-animal business.
Interesting Fact
Despite being primarily known as a producer of veterinary medicines and vaccines, Zoetis once developed and donated a dedicated COVID-19 vaccine for animals — and supplied over 11,000 doses to more than 70 zoos and sanctuaries across the United States. Those doses were used to vaccinate dozens of mammal species (including gorillas, orangutans and bonobos) — a historic first in vaccine history.
Competitors
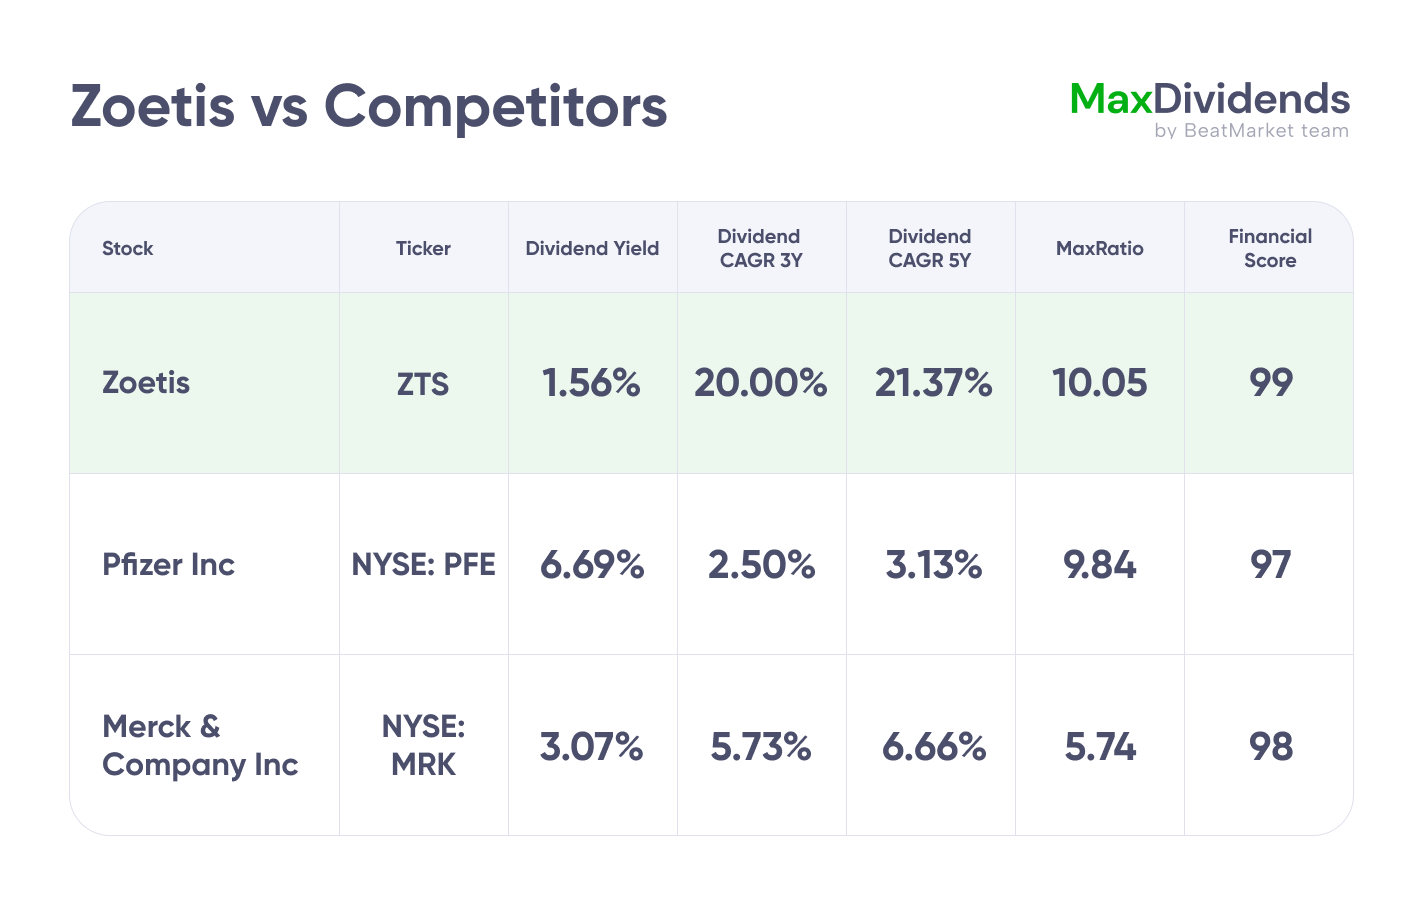
1. Pfizer Inc (NYSE: PFE)
Financial Score: 97 / 99
Industry: Drug Manufacturers - General
Global pharmaceutical and biotech powerhouse: Pfizer develops, manufactures and markets medicines and vaccines for internal medicine, oncology, immunology, rare diseases and more.
2. Merck & Company Inc (NYSE: MRK)
Financial Score: 98 / 99
Industry: Drug Manufacturers - General
Global pharmaceutical & biotech leader: Merck develops, manufactures and markets a wide range of medicines, vaccines and biologics for human health — oncology, vaccines, cardiology, immunology — plus a substantial portfolio in animal-health and veterinary products
Final Thoughts
Zoetis shows a long and consistent record of dividend growth — 12+ years of consecutive increases.
Its current payout ratio is modest (about 33–34 %), leaving the company with solid capacity for reinvestment and growth.
The annual dividend of $2.00 per share delivers a yield in the ballpark of ~1.7–1.8 %, which may seem moderate — but it’s supported by stable free cash flow, solid profitability and diversified global business.
Zoetis’s business is diversified across both companion animals and livestock, across multiple product lines (vaccines, medicines, diagnostics), which adds resilience against sector‑specific or regional fluctuations.
Conclusion: Zoetis isn’t a high‑yield “income play” — but for those seeking steady dividend growth and a fundamentally sound, resilient business with potential for long‑term appreciation, Zoetis presents a compelling option.
Undervalued \ Overvalued \ Fairly Valued
Compare the P/E ratios of competitor companies to assess whether the stock you’re considering is overvalued. We calculate the average P/E among competitors as a benchmark.
If a company’s current P/E is 20% or more below the competitor average, it is considered undervalued.
If it is 20% or more above, it is considered overvalued.
The P/E ratio is calculated by dividing the market value per share by earnings per share (EPS).
Fairy Valued

Analysts Consensus
Most recent analyst polls place Zoetis firmly in the “Buy / Moderate Buy” category. As of the latest published estimates:
The average 12‑month price target sits at $178.89, which implies a potential upside of roughly +40–47 % from current levels.
Consensus ranges show a low estimate around $130 and a bullish high estimate up to $244 — reflecting the divergence of views among analysts but also underscoring the upside potential under a favorable scenario.
Rating breakdown: many firms still call ZTS a “Buy” (or “Strong Buy”), while a smaller portion lean “Hold.” There are currently no “Sell” ratings among the major coverage.
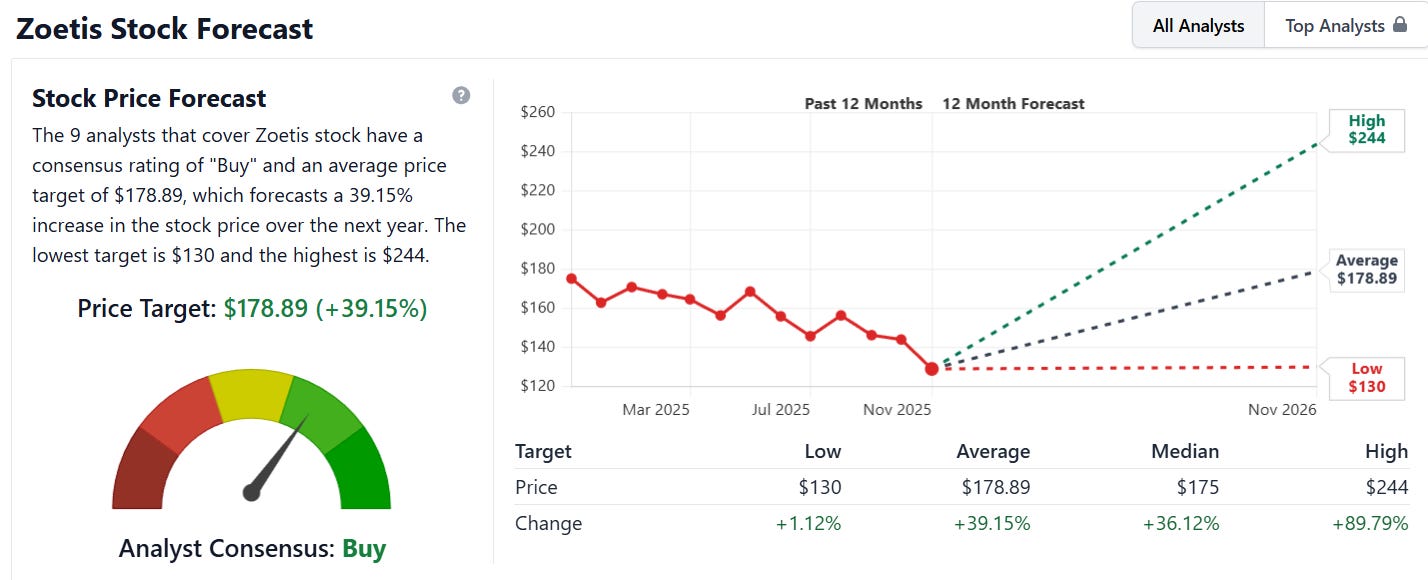
In short — while some caution remains, the broad analyst community appears optimistic: at today’s price, Zoetis is seen by most as undervalued with material upside, supported by a stable business model and growth outlook.
To your wealth, MaxDividends Team